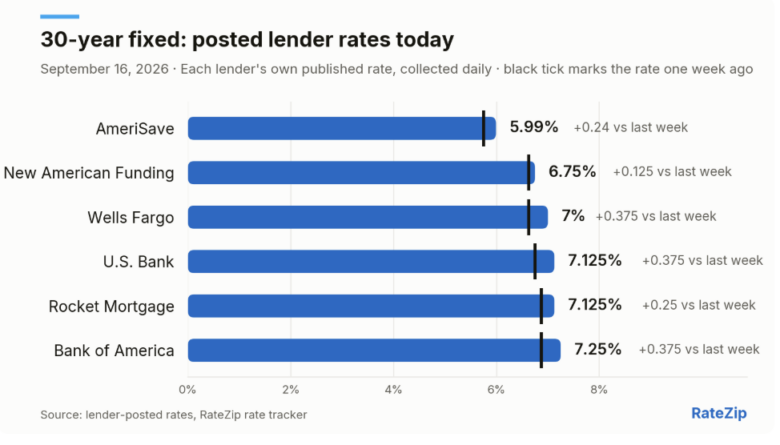
For anyone shopping a mortgage this week, Wednesday brought another round of small, unwelcome nudges. Bank of America lifted its posted 30-year fixed rate to 7.25% and its 15-year to 6.5%, U.S. Bank moved its 30-year to 7.125%, and Rocket Mortgage pushed its 15-year fixed to 6.625%, a quarter-point jump in a single morning.
None of those moves is dramatic on its own. Stack them up, though, and a pattern shows. Rocket’s increase is its seventh in the past three weeks, and its posted 15-year fixed has climbed 0.635 points over that stretch. Nationally, Freddie Mac’s Primary Mortgage Market Survey put the average 30-year fixed at 6.76% for the week ending September 10, up from 6.71% the week before. The 10-year Treasury yield, the benchmark long-term mortgage pricing most closely tracks, closed Monday at 4.97%, up 19 basis points over the past week.
The spread is the story
Here is the part that matters more to a borrower than any of those daily changes. Among the six lenders posting a 30-year fixed rate Wednesday, AmeriSave’s 5.99% sat 1.26 points below Bank of America’s 7.25%. On a $400,000 loan, that spread works out to about $333 a month. On any given morning, the difference between lenders is far larger than the day-to-day movement of any one of them.
Posted rates carry each lender’s own assumptions about credit, points and loan size, which is why the APR is the fairer cross-lender comparison: AmeriSave’s 30-year APR is 6.499%, Bank of America’s 7.481%.
Buyers have leverage, and many are not using it
The higher-rate backdrop is landing on a market where buyers already hold the upper hand in one respect. “The number of months it would take to exhaust the total inventory at the current sales pace has grown to 4.9 months’ supply—its highest level in over ten years. The ample supply of homes for sale on the market is giving homebuyers better opportunities to negotiate,” Lawrence Yun, chief economist at the National Association of REALTORS®, said in a statement on the group’s August existing-home sales report.
Yet fewer buyers are signing up for new construction. Applications to buy newly built homes fell 6% from July and 5.5% from a year earlier in August, a fifth straight monthly decline, according to MBA’s Builder Application Survey as reported by HousingWire. The FHA share of those applications rose to 35%, a three-month high.
Homeowners are borrowing against what they already have
Where borrowers are showing up in force is home equity. RateZip’s Mortgage Demand Index, built from the mortgage inquiries consumers submit across its network, shows August inquiry volume 11% higher than July’s and 157% higher than August 2025’s. Over the three months through August, home-equity products, HELOCs plus reverse mortgages, drew 76% of inquiries, versus 43% in the same months a year earlier, while refinance shrank from 39% of the mix to 2%.
That leaves the housing market in an odd standoff: more homes to choose from, more room to haggle, and financing that keeps getting a little more expensive. “There are more homes for sale than a year ago, which is good news for buyers who are ready to move, but until rates ease, many households will likely stay on the sidelines a little longer as renting is still the more affordable substitute,” Mischa Fisher, Zillow’s chief economist, said in the company’s August market report.
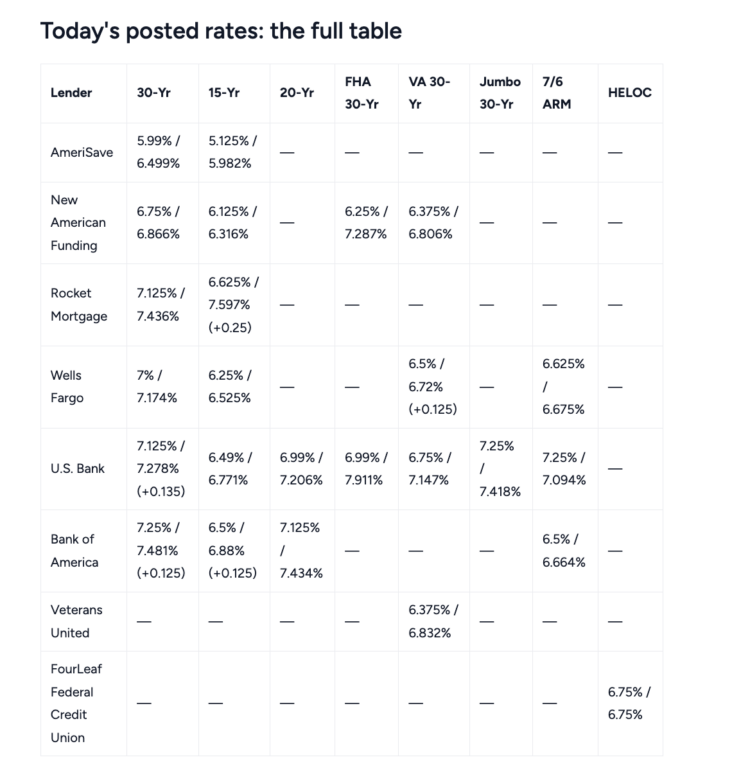
Rates are each lender’s own published rate as of 9:50 a.m. ET, collected from their public rate pages and feeds. The APR is the better cross-lender comparison; a figure in parentheses is today’s change; a ‘—’ means the lender doesn’t post that product. How we collect and publish this: our rate methodology.
Read more
RateZip is operated by Peklava LLC, DBA RateZip, a licensed mortgage broker (NMLS ID 1592292). We are compensated by some of the partners shown on this page, which may affect which offers appear and where. It does not affect our reporting or our recommendations. Rates shown were last updated September 16, 2026 at 9:50 a.m. ET. See our editorial standards and how we use AI.
How we track rates: methodology. Found an error? Tell us.
Ask us! What questions do you have about content, strategy, pop culture, lifestyle, wellness, history or more? We may use your question in an upcoming article!
Like MediaFeed’s content? Be sure to follow us.
This article originally appeared on RateZip and was syndicated by MediaFeed.co.