A homebuyer seeing the same mortgage interest rate at two lenders can still face different upfront charges. Tuesday’s posted conventional 30-year examples at Wells Fargo and Rocket Mortgage both show 7.5% interest, but disclose different points and APRs. With Freddie Mac’s weekly average at 7.03%, the price of securing an advertised rate is another part of the financing bill.
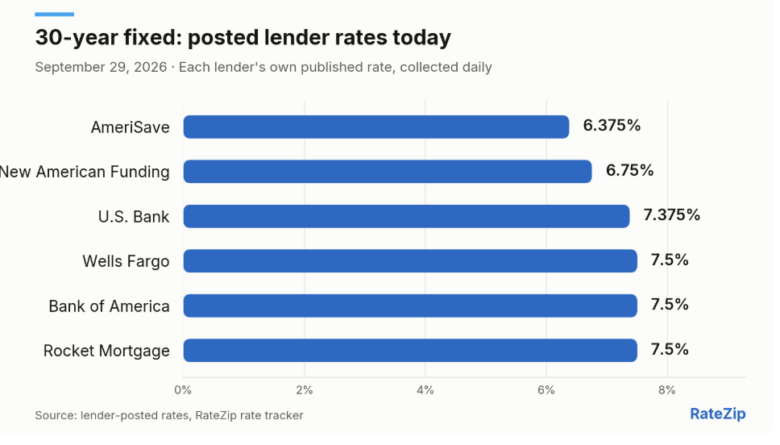
Wells Fargo’s September 29 example lists $2,400 in points and a 7.654% APR for a $400,000 Austin purchase with $80,000 down. Rocket’s example lists 2 points ($7,000) and a 7.82% APR on a $350k loan with a 740 credit score. These are different loan and eligibility scenarios, not matched offers for one borrower. What they demonstrate is that an identical advertised interest rate does not settle how much cash a loan requires upfront.
Points are an upfront charge paid to lower the interest rate, as Rocket’s rate page explains. The Consumer Financial Protection Bureau distinguishes APR from interest because APR also incorporates points and other borrowing charges. A rate-to-APR gap is therefore a reason to examine the fees behind a quote; the interest figure alone leaves those charges out.
The strain of financing a purchase is also showing up in a builder’s account of buyer behavior. In KB Home’s September 22 results release, Executive Chairman Jeffrey Mezger said, “Higher mortgage interest rates have further pressured affordability,” and also cited geopolitical uncertainty and broader economic headwinds behind buyer caution. The company reported net orders down 12% from a year earlier despite an 8% increase in its average community count. Its quarter ended August 31, before the latest September survey readings; this is the builder’s own experience, not a national sales measure.
Freddie Mac’s weekly benchmark has risen from 6.65% on August 20 to 7.03% on September 24; the preceding week’s reading was 6.95%. Its survey population is conventional, conforming purchase loans with excellent credit and 20% down. For a hypothetical $400,000 loan amount over 30 years, the latest weekly change raises principal and interest from $2,647.79 to $2,669.27, or $21.48 a month. That illustration is not an offer and excludes taxes, insurance, mortgage insurance, points, fees and closing costs. The recurring payment and the cost of obtaining the rate are separate demands on the buyer’s budget.
The CFPB’s comparison guidance brings those demands together on the Loan Estimate. It directs borrowers to compare origination charges, specified services and lender credits, then use the page-three figures to calculate interest and fees paid over five years by subtracting principal repaid from the total paid. That comparison puts upfront costs alongside the expense of carrying the loan — the information that two matching interest-rate advertisements leave unresolved.
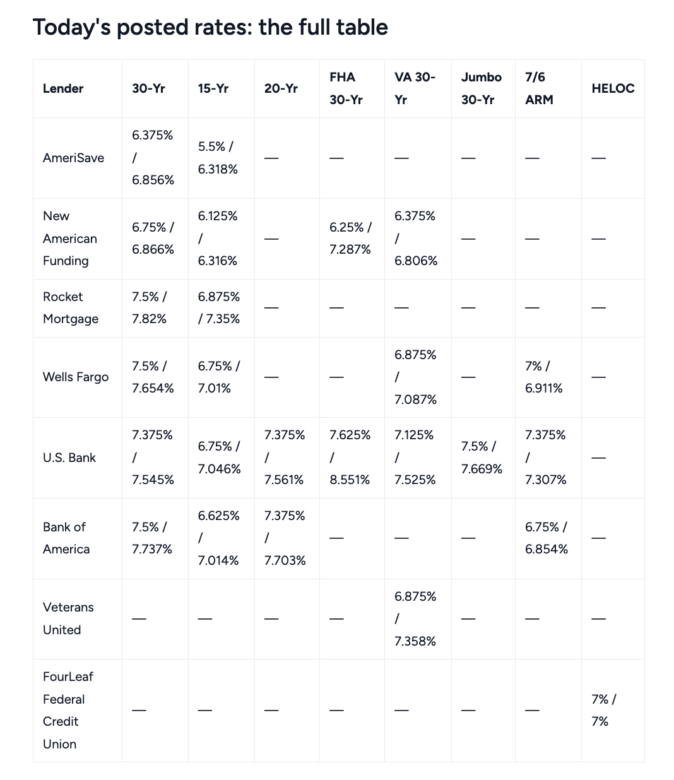
How we collect and publish rates
For closed-end mortgages, APR includes interest and certain loan charges; HELOC APR excludes fees. Adjustable-rate APR is not a maximum future rate. See the CFPB explanation.
National mortgage-rate benchmark cited in this article. Source: Freddie Mac Primary Mortgage Market Survey via FRED®, Federal Reserve Bank of St. Louis.
RateZip is operated by Peklava LLC, DBA RateZip, a licensed mortgage broker (NMLS ID 1592292). We are compensated by some of the partners shown, which may affect which offers appear and where. It does not affect our reporting or recommendations. See our editorial standards.
Read more
RateZip is operated by Peklava LLC, DBA RateZip, a licensed mortgage broker (NMLS ID 1592292). We are compensated by some of the partners shown on this page, which may affect which offers appear and where. It does not affect our reporting or our recommendations. Rates shown were last updated September 29, 2026 at 12:06 p.m. ET. See our editorial standards and how we use AI.
How we track rates: methodology. Found an error? Tell us.
Ask us! What questions do you have about content, strategy, pop culture, lifestyle, wellness, history or more? We may use your question in an upcoming article!
Like MediaFeed’s content? Be sure to follow us.
This article originally appeared on RateZip and was syndicated by MediaFeed.co.