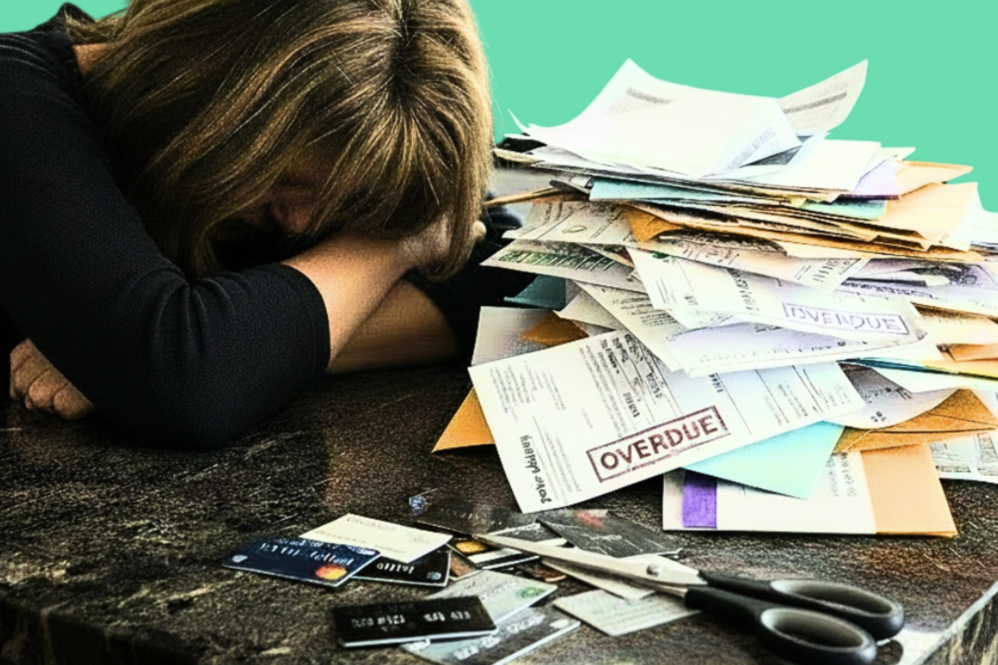
Women over 50 often find themselves deep in debt through no fault of their own. After getting hit with a death, divorce, disability, or a diagnosis, financial chaos can follow. Medical bills pile up. Years lost to unpaid caregiving. Income drops or disappears. As balances climb, shame sets in.
That shame is what keeps many women from getting help. They’re trained to figure it out. Do it on their own. So when facing a debt that won’t go away, women don’t even consider the B word: bankruptcy. For women 50+, raised to take care of everyone and everything else, bankruptcy carries a heavy and deeply gendered stigma that punishes them for surviving illness and loss, while keeping relief out of reach.
But carrying the burden alone hurts women even more, putting retirement and their future at risk. Waiting for a Hail Mary. Enduring more pain instead of getting relief.
The good news is that there are options.
Filing for Bankruptcy In Midlife
Even considering bankruptcy can be a tough pill to swallow. While it can stir up a lot of feelings and feel weighted with shame, it’s happening more than you think.
According to AARP, 47% of bankruptcy filings in 2024 were made by people age 50 and older. Not only that, but research has shown bankruptcies among those 65 and older rose from 4.5% in 2002 to 18.7 in 2022, and this demographic is growing. Women are overrepresented among bankruptcy filers, particularly among single-parent households.
What’s driving the disparity? Women often take on unpaid caregiving for children and parents. Earn less. Live longer and have higher rates of illness. So when debt—whether from bad luck or profit-driven health care—becomes too much, it’s not a personal failure to file for bankruptcy. It’s a survival tactic and a way to take back control in an unfair world.
Bankruptcy As a Reset
Despite the stigma around bankruptcy, it can be a lifeline and a way to balance the scales, especially for middle-aged women.
“Bankruptcy is a tool to manage your debts. It’s something that’s set up under federal law to ensure that people are treated fairly, and that creditors understand when people cannot afford to pay their debts back,” said Ashley Morgan, bankruptcy and debt attorney at Ashley F. Morgan Law.
When most people think of bankruptcy, they’re typically thinking of Chapter 7 bankruptcy. Through this process, nonexempt assets may be sold to repay creditors, though many people keep most or all of their property because it is exempt under federal or state law. Some debts may also be discharged, which can provide a fresh start. For those who qualify, the process can take several months.
Chapter 13 bankruptcy allows people with regular income to repay all or part of their debts through a court-approved plan, usually over three to five years. Under this plan, many people can keep their property while catching up on missed payments and repaying debts over time.
No, bankruptcy isn’t a magic wand. But it provides structure, relief, and a path forward. And when heading into retirement, every dollar counts. (Related: Your Money, Your Values, Your Advisor—In That Order)
What to Know About Bankruptcy and Retirement
Shame can keep women stuck instead of seeking solutions like bankruptcy, but delaying action can put them in an even more vulnerable position. Women who wait risk raiding their retirement accounts to get the monkey off their back—a move that could ultimately backfire and come with taxes and penalties if younger than 59 ½.
“Federal law requires qualified retirement accounts to be either exempt or excluded, which basically means they can’t be touched by the bankruptcy court,” said Morgan.
Retirement accounts like 401(k)s and pension plans? They’re generally protected in bankruptcy, but the rules and dollar limits can depend on the account type and the exemptions available in your state. Ask a bankruptcy attorney before assuming every account is fully protected. As for Social Security retirement benefits, they’re typically protected as well, though how funds are held and whether they have been commingled with other money can matter. Women don’t need to jeopardize an already precarious future by touching their retirement to pay down debt.
“I have a lot of people who I wish could have come talk to me sooner, because they did do everything to try to get out of bankruptcy. I see plenty of people where they’ve used half their retirement to try to pay down debt, and it would have been virtually protected otherwise,” said Morgan.
Want more? Get PROVOKED’s free Thursday newsletter. Sign up at PROVOKEDMagazine.com.
What About Your Credit?
Bankruptcy can stay on a credit report for up to 10 years for Chapter 7, according to credit bureau Experian. That fact alone can deter women from bankruptcy. The shame. The credit hit. It can feel like too much.
But women who are already behind on bills and facing enormous debt may not have the best credit already.
“People think that their credit is going to be worse than where they’re starting. But if you’ve already missed payments or you’re maxed out on your credit cards, bankruptcy may actually improve where your credit is at,” said Morgan.
The credit impact is not forever. Equifax noted that credit can begin to recover after bankruptcy, especially when someone makes payments on time and avoids taking on new debt. So while the effect on credit can’t be overlooked, neither can the potential relief waiting on the other side.
Enjoyed this story? Read more from PROVOKED at provokedmagazine.com.
Taking Back Control
Women over 50 have enough reasons to feel overwhelmed. Debt doesn’t have to be one of them. For those who feel suffocated by their balances, bankruptcy may provide breathing room.
“Bankruptcy is a legal and financial decision. It’s not a moral and ethical one, so only you can decide if bankruptcy’s right for you,” said Morgan.
It’s not giving up. Businesses use bankruptcy as a tool all the time. It’s taking back agency, control, and rewriting your future. Sometimes the bravest financial move isn’t pushing through—it’s choosing relief.
Related:
- How Women 50+ Self-Sabotage Their Finances
- Sorry. Not Sorry. Leave Your Shoes At the Door
- Why So Many Women Over 50 Are Skipping the Ring and Thriving
Ask us! What questions do you have about content, strategy, pop culture, lifestyle, wellness, history or more? We may use your question in an upcoming article!
Like MediaFeed’s content? Be sure to follow us.
This article originally appeared on PROVOKED and was syndicated by MediaFeed.co.